











Markets react not only to ECB policy decisions but also to policymaker speeches and interviews, whose cumulative impact can rival formal announcements, new research finds.
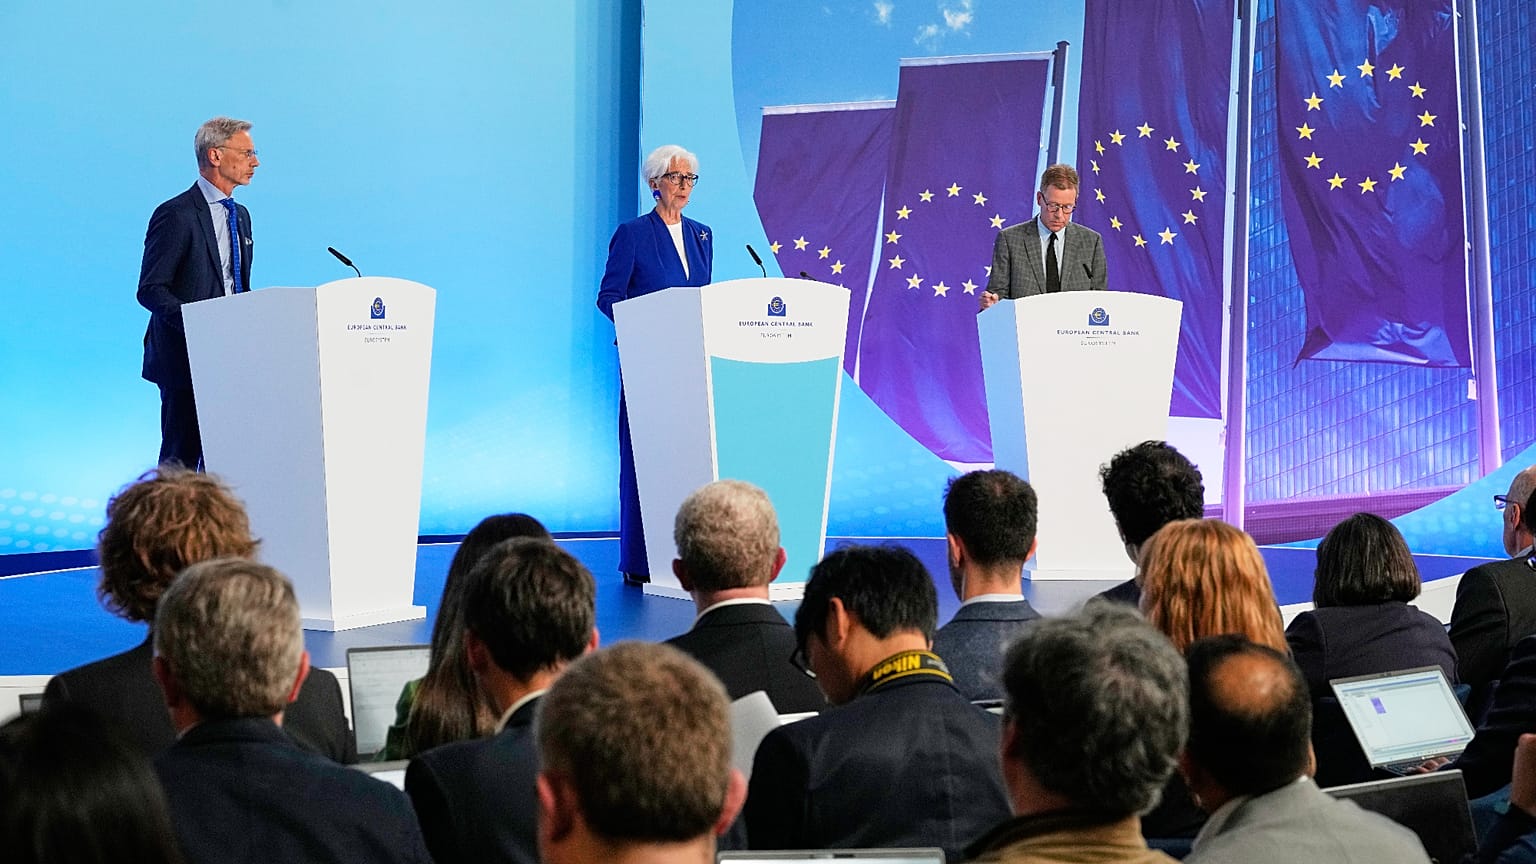
Speeches and interviews by European Central Bank (ECB) policymakers can move markets as much as formal monetary policy announcements, according to an ECB study published on Thursday.
 ADVERTISEMENT
The research, by economists Klodiana Istrefi, Florens Odendahl and Giulia Sestrieri, found that markets respond not only to the ECB's monetary policy decisions every six weeks, but also to what prominent policymakers say between meetings.
These interventions can shape market expectations about the direction of monetary policy, which in turn affects inflation and unemployment across the euro area.
While the effect may be difficult to detect from an individual speech or interview, the study found that their cumulative impact can be comparable to that of formal policy announcements.
"Our findings show that the market reaction to inter-meeting communication events is often as large as the reaction to formal announcements of Governing Council decisions," the authors wrote in an ECB blog post.
"We also find that inter-meeting communication events can help us better estimate the economic impact of monetary policy in the euro area," they added.
The authors built an "Euro Area Communication Event Study Database" with 304 formal policy decisions and approximately 5,000 public events between January 1999 and early 2024.
They examined speeches and interviews by ECB presidents, board members, and national central bank governors from Germany, France, Spain, and Italy - the four largest euro area countries.
"We found that around 45% of formal policy announcements produced a significant market reaction. By contrast, the results from inter-meeting communication events were more diverse and a smaller share of them generated a significant market reaction," the authors wrote, specifying that the results are not surprising.
"Formal policy announcements following Governing Council meetings are inherently focused on monetary policy decisions, whereas inter-meeting communication events cover a much broader range of topics," they added.
However, such public interventions are far more frequent than formal policy announcements, making their cumulative impact significant.
The study also measured which personalities affect the markets the most in speeches and interviews. In the first place, ECB presidents have "the largest impact on average," followed by national central bank governors, and then by ECB board members.
"This highlights the importance of looking beyond the ECB President and Executive Board members when analysing monetary policy communication in a heterogeneous monetary union, where countries differ significantly in their economic structures, public debt levels, and household and firm financial situations," the report says.