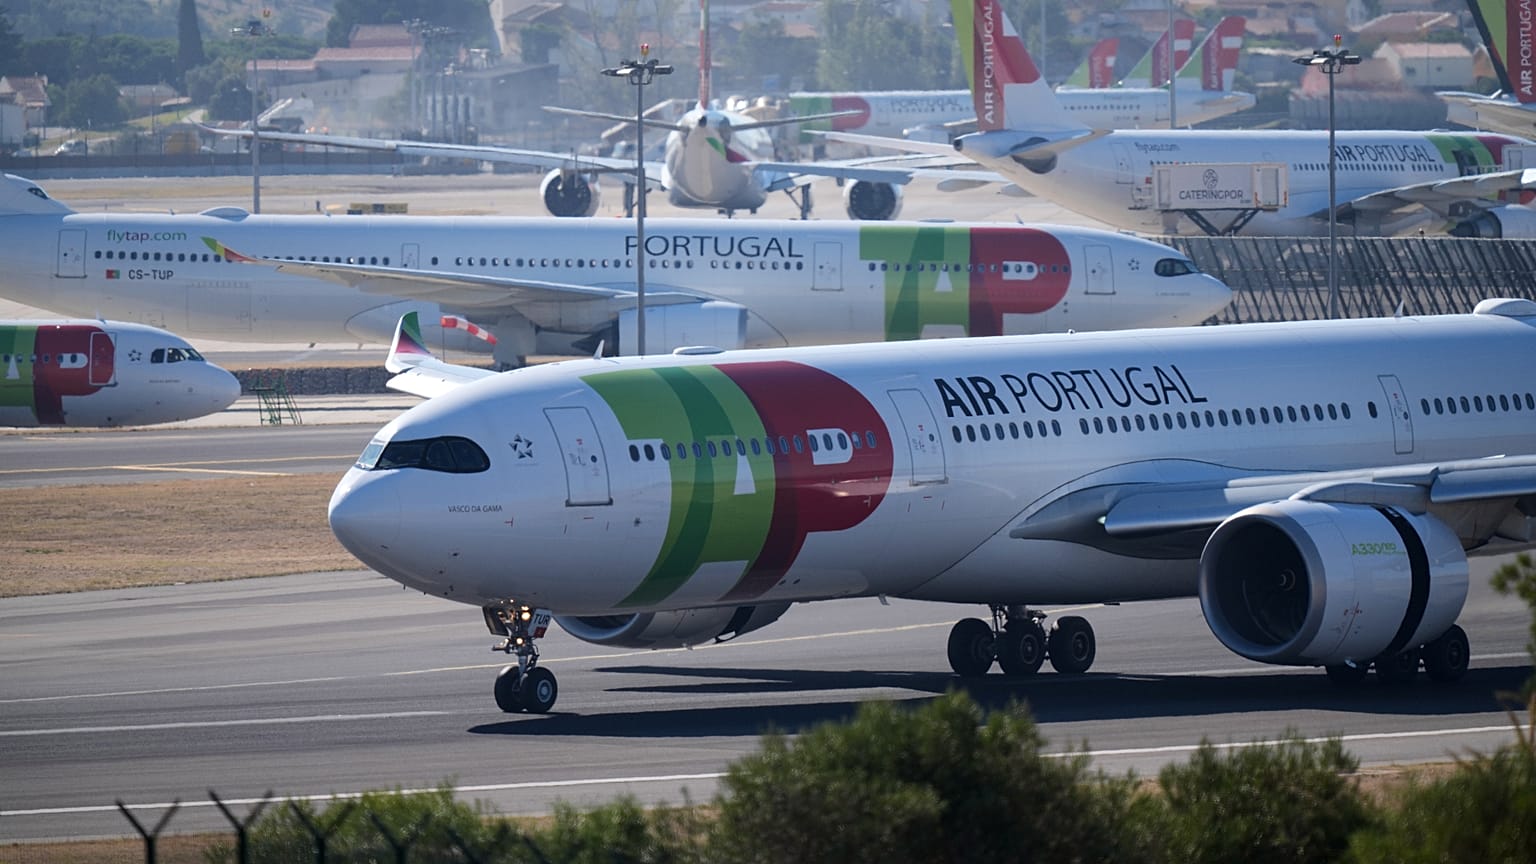


Lufthansa expects about €450 million a year in synergies from buying up to 49.9% of TAP Air Portugal for €1.2 billion, but Portugal’s continued control, lengthy regulatory reviews and the slow progress of its ITA Airways deal suggest the gains could take years to arrive.
Lufthansa's €1.2 billion winning bid for up to 49.9% of TAP Air Portugal could bring the German group around €450 million in yearly savings and extra revenue.
 ADVERTISEMENT
However, the Portuguese state's grip on the airline, drawn-out competition reviews and delays in integrating Italy's ITA Airways into the group indicate the benefits may be slow to materialise.
That is the conclusion of a report published on Tuesday by Gimme Credit, an independent corporate bond research firm.
Portugal's government picked Lufthansa's offer last week over a rival bid from Franco-Dutch group Air France-KLM.
The deal still needs final negotiations, approval from Portugal's cabinet and clearance from the European Commission, with completion pencilled in for 2028.
Lufthansa will pay €1.025 billion for 44.9%, it said, rising to up to €1.2 billion for 49.9% if it also buys shares first offered to TAP's employees, representing up to 5% of the airline, and pays a so-called ticking fee, which accrues until the deal closes.
The Portuguese state will keep 50.1%, but Lufthansa will get to name TAP's CEO, while the government will hold a majority on the board.
Lufthansa's offer valued TAP about 16% higher than Air France-KLM's and was entirely in cash, while its rival offered a mix of cash and shares.
"Lufthansa has gone a long way to secure its winning bid," Gimme Credit noted, while Lufthansa CEO Carsten Spohr called TAP "a strong and profitable airline".
TAP stayed in the black for a fourth straight year in 2025, but its net profit shrank to €4.1 million, hit by a one-off tax adjustment, and it lost €99.2 million in the first half of 2026 as fuel costs surged.
Lufthansa's management believes the synergies will come from commercial activities, better network connections, joint purchasing and cargo, according to Gimme Credit's director of European research, Cedric Rimaud.
The big prize is TAP's network to Brazil and the rest of Latin America, along with traffic between Europe and Portugal, and between southern Europe and North America.
Spohr said the deal would "sustainably strengthen our [Lufthansa's] position in the South Atlantic market".
Management expects traffic on those routes to grow by about 2% to 3% for Latin America and 6% to 7% for the others between 2025 and 2030, Rimaud said.
TAP holds 24% of seat capacity between Europe and Brazil, second only to Latin American group LATAM, according to aviation data firm OAG.
With TAP, Lufthansa’s airlines would hold 36%.
TAP also flies only Airbus jets, which make up most of Lufthansa's fleet, "bringing some natural economies of scale between the two airlines," Rimaud said, as some spending on engineering, training and maintenance can be pooled.
A long road to 2030
Lufthansa has promised to grow TAP's fleet to 117 aircraft by 2035 and invest €500 million in Portugal, the government said.
The firm has also pledged to keep TAP as a standalone airline, which, along with the state's control, "will limit the ability to rationalise operations across the whole group,” Rimaud explained.
Lufthansa expects TAP to join its transatlantic joint venture with United Airlines and Air Canada, in which the partners coordinate schedules and share revenue. It made a similar promise when it bought into ITA Airways in January 2025.
ITA is still waiting for the US Department of Transportation's approval, and its first jointly coordinated flight across the Atlantic is not due until summer 2027.
EU competition officials will also examine the joint venture, and Rimaud sees "revenues from this integration unlikely before 2030".
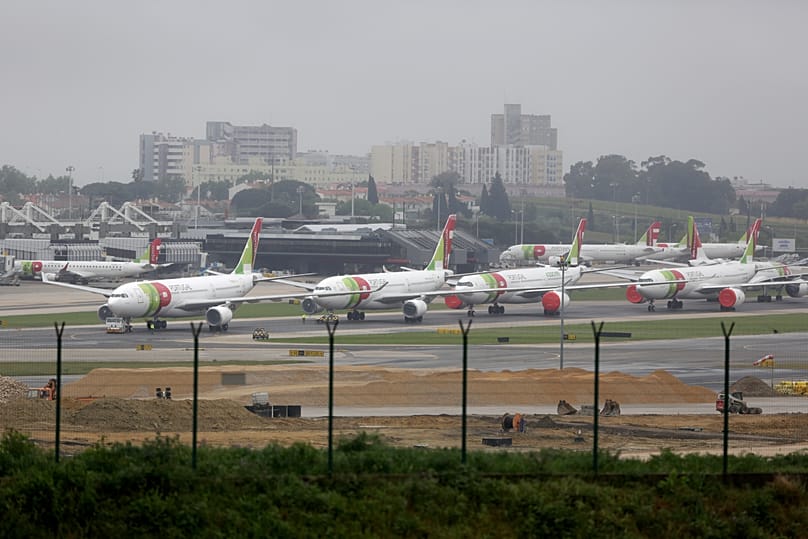
Growth at TAP's Lisbon hub is capped too, as the airport is full and a replacement will not open before 2034, according to OAG.
Lufthansa can pay for TAP from its own cash, and Gimme Credit does not expect "a significant uptick in Lufthansa's leverage". TAP's own debt poses little threat either, with no significant repayment due until its bonds mature in 2029.
Gimme Credit expects Lufthansa to seek to buy the rest of TAP by 2028, after Portugal launched a process for the airline's full privatisation. It kept its "sell" recommendation on Lufthansa's bonds, noting a yield of 5.52%, against 6.9% on Air France debt.
While it expects TAP to join the transatlantic venture eventually, Gimme Credit sees that happening "over a longer time horizon than what management promises".